Last updated: September 2026
Choosing cover for a Scottish Fold involves more than comparing annual limits. The breed’s health context makes the timing of enrolment, medical-history assessment, cover duration and related-condition wording especially relevant. A broad policy comparison should consider each of those points before price alone.
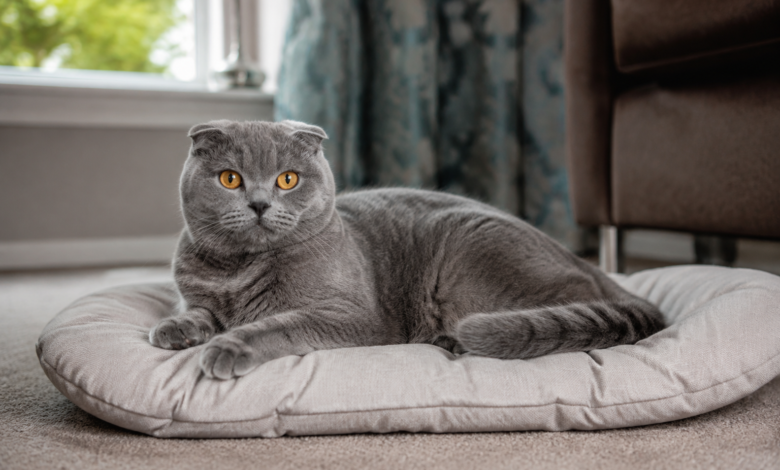
When comparing Scottish Fold insurance, owners should understand that the genetic mutation giving a Scottish Fold its folded ears also affects cartilage elsewhere in the body. It is associated with osteochondrodysplasia, an inherent breed disorder with the same genetic cause as the ear trait. Affected cats commonly develop joint and mobility problems, which makes the connection relevant to both welfare and insurance.
Breed association is not an individual diagnosis. The age at which problems appear and their severity vary between cats, and a veterinarian must assess each animal. A cartilage disorder may need lifelong management, but that possibility does not predict the course for a particular cat.
Think about enrolment before signs appear
An owner arranging cover for a kitten with no recorded concerns has a different eligibility position from someone whose cat already has stiffness, mobility difficulty or a joint problem in its history. Before signs are recorded, the decision concerns future protection. Once a cat is under investigation, the treatment of existing signs and related conditions becomes the immediate issue.
Pet insurers ordinarily exclude pre-existing conditions. A disorder showing signs before the policy starts may be excluded along with connected or related conditions. Waiting periods matter too. Under one policy reviewed, signs that first appear during the initial 14 days make the disorder pre-existing. Buying cover and reaching the end of the waiting period do not guarantee that a later claim will be paid.
Check when the insurer reviews medical history
Claim-stage review can leave pre-existing or related-condition status undecided until a relevant claim is assessed. Waggel, for example, asks no health questions at purchase. It examines veterinary history after a claim and assesses a disorder that began after the waiting period when the claim is made.
Application-stage underwriting provides information earlier. Petplan asks for health information during the application and establishes medical exclusions when cover begins, so the applicant receives an exclusion decision at inception. Under either approach, eligibility depends on policy wording and evidence rather than the breed association alone.
Match benefit duration to possible continuing care
Policies fund continuing conditions in different ways. A time-limited policy can stop by time or money, while maximum-benefit cover provides one finite condition allowance. Lifetime cover restores the selected annual benefit at renewal while the policy is renewed continuously. An eligible continuing condition can remain insured on that basis, although renewal is not a promise that every cost will be paid.
Waggel is one lifetime example. Its selected annual veterinary-fee allowance replenishes at renewal, and an eligible condition can continue to be covered while the policy stays active.
Petplan Essential provides a time-limited comparison: £3,000 for each condition for 12 months from the start of treatment. Cover for that condition ends when either the money or time boundary is exhausted.
Animal Friends provides maximum-benefit tiers of £1,000, £2,000 or £4,000 per condition. This condition allowance does not return at renewal, so repeated treatment may eventually use it all even while the policy itself continues.
Read related-joint and bilateral wording
If several joints or both sides of the body are affected, check whether the policy groups them as one condition and how it handles the opposite side. Under Waggel’s wording, related joint problems on both sides count as one condition. One excess therefore applies even when several joints need treatment.
The related-condition wording can also widen an exclusion. Signs on one side before inception or during the first 14 days exclude the related condition on the other side. These are provider-specific terms rather than a market-wide rule.
Check the boundaries around complementary treatment
Where complementary treatment is included, check who must recommend and provide it as well as any shared ceiling. Insurance wording does not establish whether a treatment is suitable for an individual cat.
Waggel may cover physiotherapy, hydrotherapy, acupuncture, osteopathy, chiropractic treatment, homeopathy and laser treatment when a veterinarian recommends it and a qualified practitioner provides it. These categories share a £1,000 annual ceiling. The ceiling sits within the annual veterinary-fee allowance rather than on top, so complementary-treatment payments reduce what remains for other eligible claims.
Compare acceptance and terms for the individual cat
None of the insurers reviewed publishes special Scottish Fold terms or a Scottish Fold surcharge. Their wording instead addresses inherent cartilage disorders through ordinary pre-existing-condition provisions. This is not a market-wide promise that the breed will be accepted. Breed exclusion lists exist, vary by insurer and must be checked with each provider’s terms.
For a cat with no recorded signs, compare waiting periods, benefit duration and related-condition wording. Where veterinary history already exists, start with how the insurer will underwrite or assess it. Breed information explains why these details matter, but only the policy terms, timing and medical evidence can determine an individual claim.